Mike Prenesti, The Mortgage Jedi
16 years helping Las Vegas homebuyers find the right loan. NMLS #1033445.
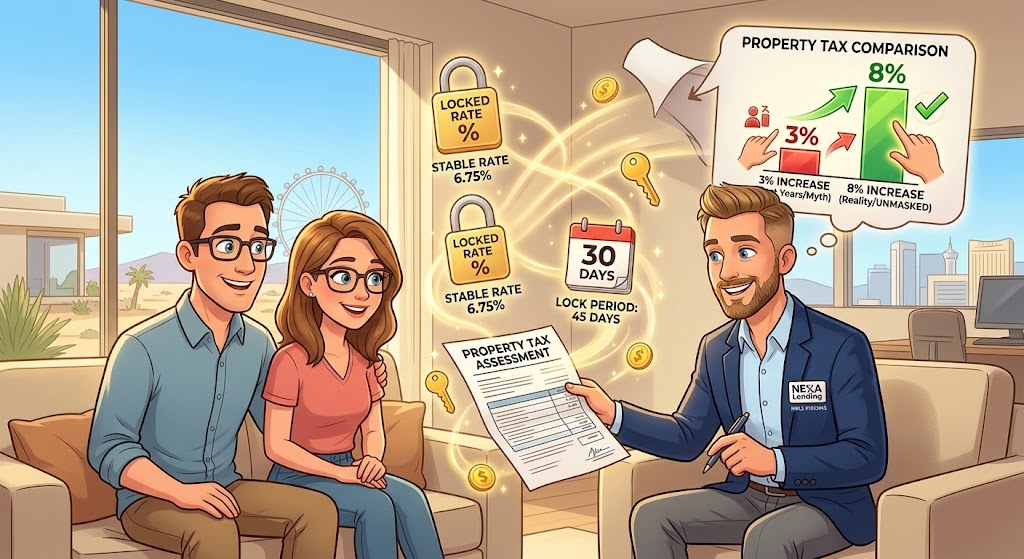
A buyer closed on a $475,000 home in Las Vegas last year and never filed one form with the county. Eighteen months later her property tax bill jumped by 8% instead of 3%. Nobody told her the difference, or that it wasn't automatic.
That single missed form cost her real money. So let's fix that before it happens to you.
Nevada's Property Taxes Are Actually Low. Here's the Catch.
Nevada has one of the lowest effective property tax rates in the country, around 0.47% statewide. Clark County runs almost identical at about 0.48%. Compare that to states like Texas or New Jersey, where effective rates run two to three times higher, and Nevada looks like a great deal.
It is a great deal. But "low rate" doesn't mean "simple math," and the way Nevada calculates your bill trips people up constantly.
How Your Bill Actually Gets Calculated
Nevada doesn't tax your home's full market value. It taxes something called assessed value, which is 35% of the property's taxable value. Taxable value is based on the land's cash value plus the replacement cost of the structure, minus depreciation.
Once you have the assessed value, the county applies a tax rate per $100 of that assessed value. Clark County has 117 different tax districts, so your neighbor two streets over in a different district can pay a noticeably different amount than you, even on a nearly identical house.
On a median-priced $475,000 Las Vegas home, that typically works out to somewhere between $2,200 and $2,800 a year, roughly $185 to $235 a month. Where you land in that range depends entirely on your specific tax district, so don't budget off a sale price alone. Look up the actual parcel with the Clark County Assessor once you have an address.
The Part Almost Nobody Explains: Nevada's Tax Cap
This is the piece that actually matters for your wallet over time.
Nevada caps how much your annual property tax bill can increase, not the tax rate itself, the increase. If you live in the home as your primary residence, that cap is 3% a year. If it's a second home, a rental at market rent, vacant land, or new construction, the cap can run as high as 8% a year.
A few details that trip people up:
- The 3% cap applies to one primary residence per person, not every property you own.
- New construction does not get the cap in its first fiscal year. The cap starts the year after.
- When ownership changes hands, the abatement can drop off the property. After you close, watch for a postcard from the county and reapply so the 3% cap actually attaches to you.
Over ten years, that gap between 3% and 8% compounds into real money. On that same $475,000 home, the difference between the two caps can add up to close to $2,000 by year ten.
Here's the mistake that catches buyers off guard: closing on your home does not automatically apply the 3% primary residence cap. You have to file a primary residence claim with the Clark County Assessor yourself. The county may mail you a claim card, but if that mail gets missed during a move, which happens constantly, you get defaulted to the higher cap without ever knowing it.
What To Actually Do About It
File your primary residence claim with the Clark County Assessor as soon as you close, not whenever you get around to it. Don't wait for a mailer that might not reach you at your new address.
If you already closed a while back and you're not sure whether it's on file, it's worth a five-minute call to the Assessor's office to confirm. Better to check now than find out at your next tax bill.
If you ever disagree with your home's assessed value, Clark County has an appeal window that runs from December through January 15 each year. Miss that window and you're locked in for the cycle.
How It Actually Gets Paid
Most buyers don't write a check to the county directly. Your lender collects a monthly amount with your mortgage payment, holds it in an escrow account, and pays Clark County when the bill comes due. I break down exactly how that works in Escrow Accounts Explained.
That means a miscalculated cap doesn't just show up as a surprise bill once a year, it can quietly push your monthly payment up when your lender recalculates your escrow. Buyers who understand this ahead of time avoid the surprise. Buyers who don't sometimes call their lender confused about why their payment went up when nothing about their loan actually changed.
Why It Matters for What You Can Actually Borrow
Property tax is part of your total monthly housing payment, so it counts toward your debt-to-income ratio right alongside principal, interest, and insurance. A higher tax bill can lower the purchase price you qualify for, even if your rate stays exactly the same. If you want the full breakdown on that math, start with What Debt-to-Income Ratio Actually Means.
If you're buying in Las Vegas or already own here, get the primary residence claim filed and confirmed. It's one of those five-minute tasks that quietly protects you for years.
Frequently Asked Questions
How much are property taxes on a home in Las Vegas? On a median-priced home around $475,000, expect somewhere between $2,200 and $2,800 a year, or roughly $185 to $235 a month. The exact number depends on which of Clark County's 117 tax districts your home falls in, since rates vary by location even for similarly priced homes.
Why is my property tax bill higher than my neighbor's, even though our homes look identical? Clark County is divided into 117 separate tax districts, each with its own rate. Two nearly identical homes in different districts, even a few streets apart, can carry noticeably different tax bills. Your assessed value and any exemptions on file also factor in.
What is Nevada's property tax cap, and does it apply automatically? The cap limits how much your annual bill can increase, 3% a year for a primary residence, up to 8% a year for second homes, rentals, vacant land, or new construction. It does not apply automatically when you close. You have to file a primary residence claim with the Clark County Assessor yourself.
How is my Nevada property tax bill actually calculated? Your home's taxable value gets multiplied by 35% to get the assessed value. The county then applies your local tax district's rate per $100 of assessed value. It's not based on your home's full market price the way some states calculate it.
Can my property taxes really increase by 8% instead of 3%? Yes, and it happens more often than people realize. If you never filed the primary residence claim after closing, or if the property is a second home, rental, or new construction in its first fiscal year, the higher cap applies by default. Over ten years that difference can add up to close to $2,000 on a median-priced home.
How does property tax affect what I qualify to borrow? Property tax is part of your total monthly housing payment, so it counts toward your debt-to-income ratio just like principal, interest, and insurance. A higher tax bill can lower the purchase price you qualify for, even if your interest rate stays exactly the same.
Get Your Real Numbers
A tax estimate from a website is a start. The number that matters is the one built for the home you're actually buying, with the real district rate and the right cap applied.
Get started here or book time on my calendar and we'll build your real payment with the actual tax figures for that property.
Mike Prenesti, NMLS #1033445. Nexa Lending, LLC, NMLS #1660690. Equal Housing Opportunity. Licensed in Nevada. This article is for educational purposes only and is not a commitment to lend or financial advice. Tax figures are estimates, so confirm your actual bill with the Clark County Assessor. Not all borrowers will qualify. Program guidelines vary by investor and are subject to change.
Have questions about your situation?
Let's talk it through. No pressure, no obligation.
Book a Free ConsultationRelated Posts
Mortgage Broker vs. Bank: What Actually Wins You the Better Loan
A bank can only sell you what's on its own shelf. A broker shops your file across dozens of lenders to find the one that actually says yes, and says yes on better terms. Here's what that difference is worth.
Rate Locks Explained: What You're Actually Guaranteed, and What You're Not
A rate lock feels simple until you actually need it to hold. Here is what it really guarantees, how long it lasts, and what happens if your closing slips.

5 Credit Score Myths That Are Costing Homebuyers Money
Checking your own credit doesn't hurt your score. Closing old cards usually makes things worse. Here's what's actually true.