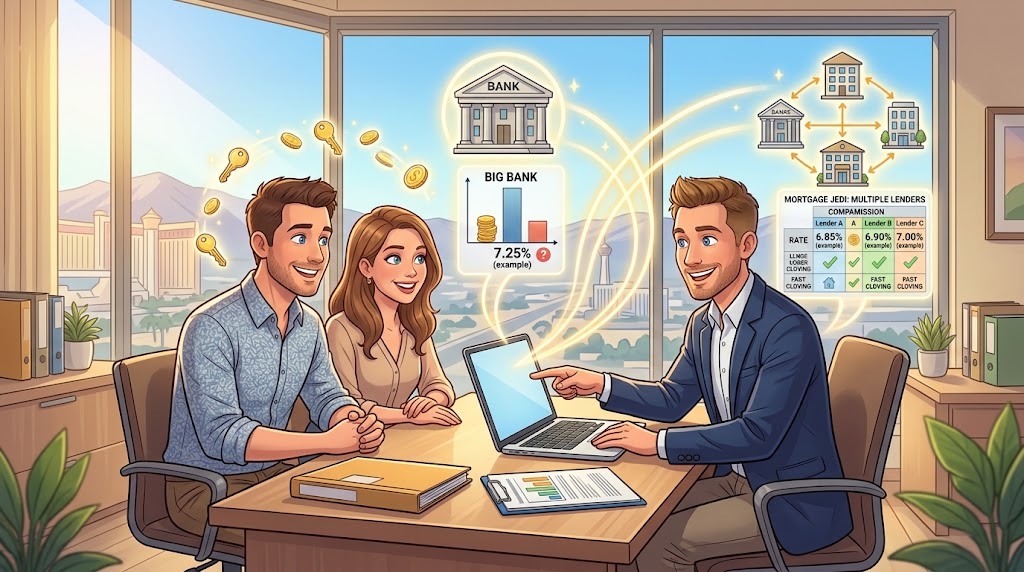
Mike Prenesti, The Mortgage Jedi
18+ years helping Las Vegas homebuyers find the right loan. NMLS #1033445.
A buyer got turned down by her bank last month. Self-employed, strong income on paper, but her tax returns had enough write-offs that the bank's underwriting software couldn't make the math work.
She almost gave up on buying this year.
Instead she came to me. Same income, same tax returns. I ran her file past four lenders who specialize in self-employed borrowers, and she closed 34 days later.
Same buyer. Same numbers. Two completely different outcomes. That's the actual difference between a bank and a broker.
A Bank Sells What's On Its Shelf
Walk into a bank for a mortgage and you get exactly one thing: whatever that bank is offering that day. One set of guidelines, one rate sheet, one underwriting box.
If your file fits that box, great. If it doesn't, the answer is no, even if your loan would sail through at the bank two blocks away.
Banks aren't wrong to work this way. They're built to sell their own products, the same way a Honda dealership sells Hondas. Nothing wrong with a Honda. It's just the only car on the lot.
A Broker Shops the Whole Market
As a broker, I'm not tied to one lender's guidelines. I work with wholesale lenders, credit unions, and specialty lenders, on top of many of the same big-name lenders banks use themselves.
When a client's file comes in, I'm not asking "does this fit my one product." I'm asking "which of my forty-plus lenders wants this file the most, on the best terms."
That's the whole job. Match the borrower to the lender who actually wants them, instead of hoping they fit whatever's on one shelf.
Where This Shows Up Most
Every borrower benefits from a broker shopping their loan. It matters most for buyers who don't fit the standard conventional box:
Self-employed borrowers whose tax write-offs make their income look smaller than it actually is. Investors who need to qualify on a property's rental income instead of personal income. Veterans who deserve a lender that actually understands VA guidelines instead of treating it like a special case. Buyers with a lower credit score who still have a real path to a loan, just not at every lender.
A bank sees one of these files and often just sees risk. A broker sees a file that fits a specific lender's exact sweet spot, and knows which lender that is.
It's Not Usually More Expensive
A common assumption is that a broker costs more since there's a middleman involved. In most cases that's backwards.
Brokers get paid by the lender, built into the loan the same way a bank loan officer's compensation is built in. You're not paying extra for the broker to exist.
What you are getting is competition working in your favor. When a broker shops your file across multiple lenders, those lenders are competing for your business. A single bank has no competition to worry about. You're just taking their number.
When a Bank Actually Makes Sense
I'll say this plainly because it's true: if you already bank somewhere, have straightforward W-2 income, strong credit, and they're handing you a genuinely competitive rate, going direct can work out fine.
The catch is you won't know if it's actually the best deal, because you're only seeing one lender's numbers. You'd have to shop it yourself to find out, which is exactly the legwork a broker already does.
The Real Question to Ask
Before you commit to any lender, bank or broker, ask this: how many options did they actually check before giving you this number?
A bank has one answer to that question. A broker should have a real one, backed by more than one lender's guidelines and more than one rate sheet.
That's the whole difference. Not who's cheaper on paper. Who's actually working the file to get you the best outcome available, not just the only one they're allowed to offer.
Let's See What You Actually Qualify For
If you've been told no, or you're just not sure whether the number you were quoted is actually the best one out there, let's find out together. No pressure, no obligation.
Get started here or book time on my calendar and I'll show you what your options actually look like.
Frequently Asked Questions
Is a mortgage broker more expensive than going to a bank?
Not usually. Brokers get paid by the lender, not by charging you more, and because a broker is shopping your loan across multiple lenders, you're more likely to land a lower rate than walking into one bank and taking whatever they offer.
Why would a bank turn someone down that a broker can approve?
A bank can only lend against its own guidelines. If your file doesn't fit that one box, self-employed income, a lower credit score, a non-warrantable condo, the bank says no. A broker has dozens of lenders with different guidelines, so there's usually one whose box you do fit.
Do brokers work with all the same lenders as banks?
Brokers work with wholesale lenders, credit unions, and specialty lenders that most banks don't offer at all, on top of many of the same big-name lenders banks use. That's a much wider shelf to pull from than any single bank has.
Is my loan less safe with a broker than with a bank?
No. Brokers are licensed and regulated the same as bank loan officers, and your loan still closes with a real, regulated lender. The difference is who's shopping for you, not who's protecting you.
When does it make sense to just go to my bank?
If you already bank there, have a straightforward W-2 income, strong credit, and they're offering a genuinely competitive rate, going direct can work fine. The risk is not knowing whether that's actually the best deal available, since you're only seeing one lender's numbers.
What's the real difference between working with a broker and a bank?
A broker shops your loan across multiple lenders to find the best combination of rate, terms, and approval odds for your specific situation, while a bank can only offer its own in-house products. That matters most for buyers who don't fit a standard conventional box.
Mike Prenesti, NMLS #1033445. C2 Financial Corporation, NMLS #135622. Equal Housing Opportunity. Licensed in Nevada. This article is for educational purposes only and is not a commitment to lend. Not all borrowers will qualify. Program guidelines vary by investor and are subject to change.
Have questions about your situation?
Let's talk it through. No pressure, no obligation.
Book a Free ConsultationRelated Posts
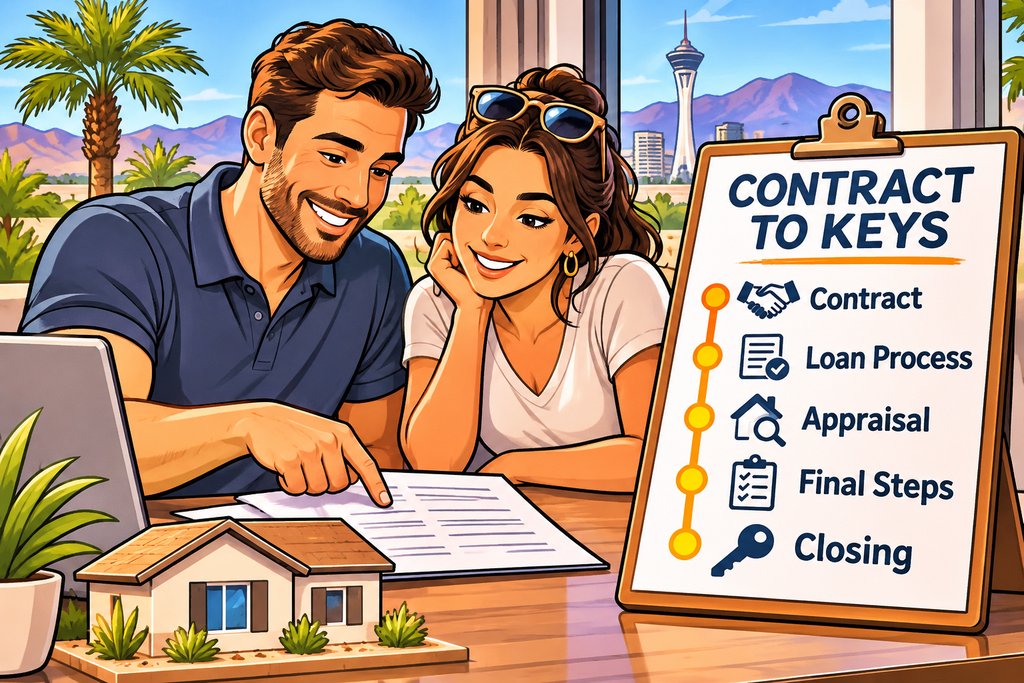
How Long It Really Takes to Close a Mortgage, Week by Week
From signed contract to keys, here is what happens each week, what slows each step down, and what you can do to keep your closing on schedule.
Renting vs. Buying in Las Vegas Right Now: What Each One Really Costs
At today's median price, owning costs more per month than renting a similar home. Here is the full math, what each path builds, and how long you need to stay.
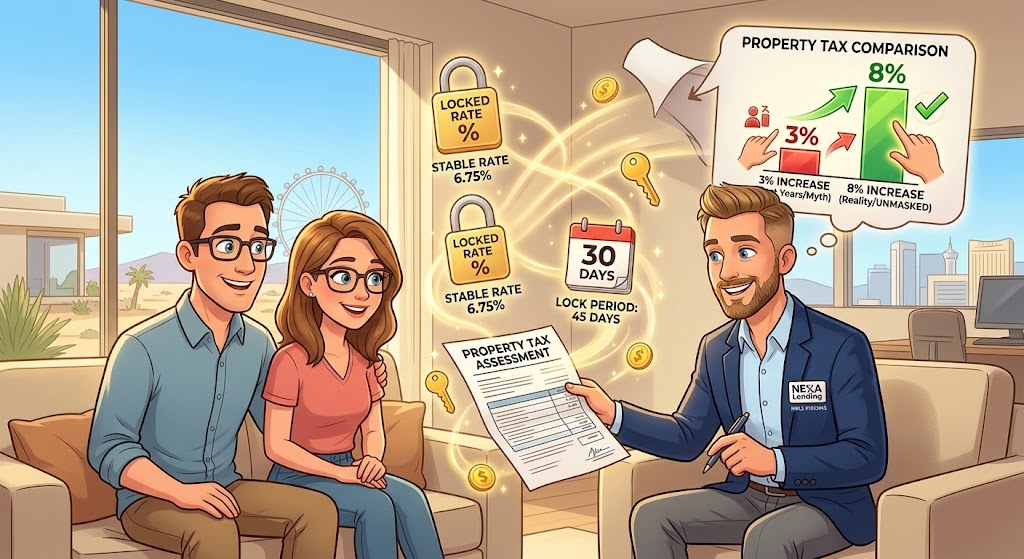
Nevada Property Taxes: What New Homeowners Actually Pay (And the Filing Mistake That Costs Thousands)
Nevada has some of the lowest property tax rates in the country, but one unfiled form can bump your annual increase cap from 3% to 8%. Here is how the bill works, what it adds to your payment, and what to file after you close.