Mike Prenesti, The Mortgage Jedi
18+ years helping Las Vegas homebuyers find the right loan. NMLS #1033445.
When you finance a condo, the lender approves two things: you and the building. A strong buyer can still get stuck on a weak project, and most of the surprises show up late in escrow.
Here is what lenders look at, how it differs by loan type, and how to check a building before you write an offer.
Where the Las Vegas Condo Market Stands
Las Vegas REALTORS reported an October median of $279,000 for condos and townhomes, down 2.1% from October 2025, according to FOX5's coverage of the report. The single-family median was $475,000.
At the end of October, 2,837 condos and townhomes were listed without an offer. For a lot of buyers, that lower price point is the way in. My first-time buyer guide for Las Vegas and my post on down payment options cover the rest of the path.
Why the Building Matters
Your unit's value depends on the association. If many owners stop paying dues, the budget gets squeezed and repairs get put off. If a lawsuit is pending, the building's finances can be at risk.
That is why lenders review project-level factors in addition to your credit, income, and down payment. The review is not a judgment on you. It is a check on what backs the loan.
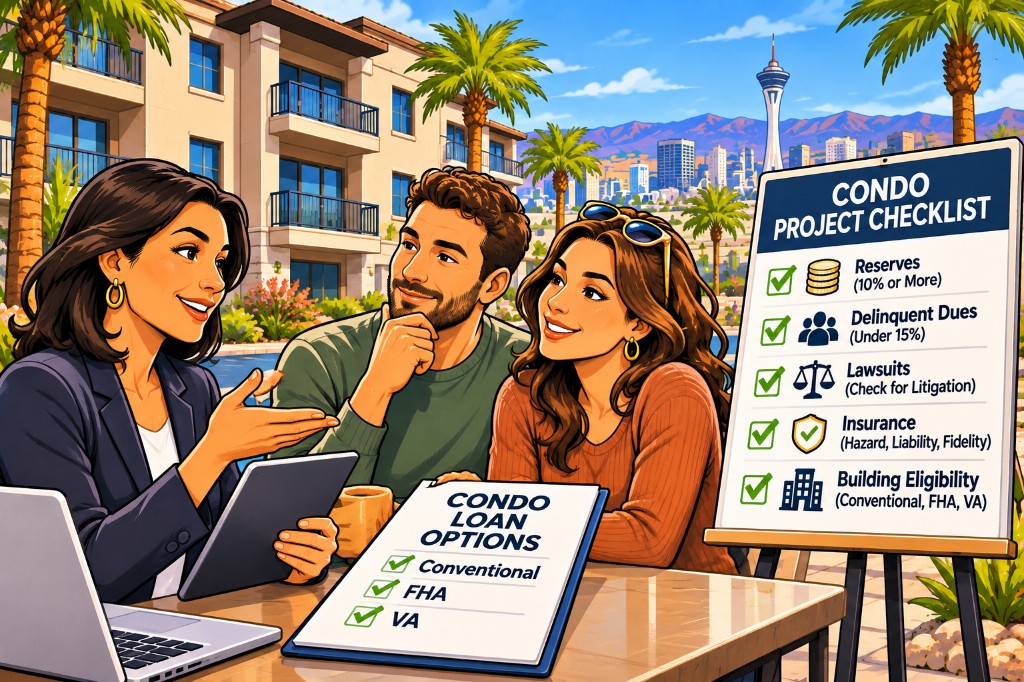
What Conventional Lenders Check
Fannie Mae's full review process sets several tests. Two are easy to understand.
- The budget must set aside at least 10% for replacement reserves and deferred maintenance.
- No more than 15% of units can be 60 or more days past due on common expense dues.
Fannie Mae's list of ineligible projects includes buildings that need critical repairs, hotel-style operations, timeshares, and projects with more than 35% commercial space. Certain pending litigation against the association can also disqualify a project, and there are limits on how many units one owner can hold.
Requirements vary by lender, and some lenders add their own rules. I check the specific building before you get attached to it.
FHA: Approved Buildings and Single-Unit Approval
For an FHA loan, the building has to be FHA approved, or the unit has to qualify under single-unit approval. HUD's 2019 rule made several changes.
- Individual units in completed, non-approved projects can be insured. In projects with 10 or more units, no more than 10% of units can be FHA insured. Smaller projects are limited to two units.
- Most approved projects need at least 50% of units occupied by owners.
- Approvals last three years instead of two.
Single-unit approval comes with paperwork. HUD's required documents list includes Form HUD-9991, the recorded CC&Rs, and evidence of master hazard, liability, and fidelity insurance. For a closer look at how FHA compares to other loans, see my post on FHA vs. conventional. Rules get updated, so confirm what applies to your file.
VA: Check the Approved List Early
VA keeps its own list of approved condominium projects. According to VA's lender pamphlet, a condominium must be approved before units in it qualify for VA loan guaranty, and projects already approved by HUD generally need no further VA review.
That pamphlet is older, so I treat it as a starting point and verify a building's current status before you commit. My post on VA loans in Las Vegas covers the rest of the process.
Nevada Gives You a Head Start: The Resale Package
When you buy a unit in a Nevada common-interest community, you can request a resale package. Under NRS 116.4109, the association must provide it within 10 calendar days of a written request.
The package includes the CC&Rs, bylaws, rules, the current operating budget, and a financial statement with a reserve summary. The resale certificate also discloses unsatisfied judgments and pending legal actions against the association, plus current and expected fees and charges. The package stays effective for 90 calendar days.
That is the best early look at the building. Send it to me as soon as you have it.
What the Dues Do to Your Qualifying
Dues are part of your monthly housing expense. Here is a hypothetical example. Say a unit has $300 a month in HOA dues, and your gross monthly income is $8,000.
- $300 a month adds 3.75 points to your debt-to-income ratio.
- At a 6.75% rate, $300 of payment room is worth about $46,200 of loan amount, counting principal and interest only.
These numbers are for illustration, not a quote. My post on Las Vegas HOA fees and your mortgage shows how lenders count dues. Also ask whether any special assessments are planned, and read my post on Nevada special assessments to see how they change your payment.
A Condo Shopping Checklist
Before you make an offer, ask for these.
- The resale package, including the budget and reserve summary.
- The monthly dues and what they cover.
- Any pending litigation or planned special assessments.
- How many units are owner occupied and how many are rented.
- Whether the building is on the FHA or VA approved lists, if you plan to use those loans.
- The master insurance policy details. You will also need your own interior policy, and my post on homeowners insurance costs shows what to expect.
If the reserve summary shows major components near the end of their life, ask how the association plans to pay for them. A big repair can mean a big assessment.
Send Me the Listing
If you are looking at a condo, send me the address and the name of the building. I will check it against the loan types you are considering, and I will tell you honestly what I find, before you spend money on an inspection or appraisal.
See if we're a fit or book a call directly.
Frequently Asked Questions
Can I use an FHA loan to buy a condo in Las Vegas?
Yes, if the building is FHA approved or the unit qualifies under single-unit approval. HUD's 2019 rule lets individual units in completed, non-approved projects be insured, as long as no more than 10% of units in projects with 10 or more units are FHA insured. Ask your lender to check the project before you write an offer.
Why does a lender review the whole building and not just my unit?
The building's finances and condition back the value of your unit. If many owners are behind on dues, reserves are thin, or the association is in a lawsuit, the risk to your unit goes up. Lenders review those project-level factors alongside your credit and income.
What do conventional lenders look for in a condo project?
Fannie Mae's full review looks at items such as whether the budget sets aside at least 10% for replacement reserves and whether more than 15% of units are 60 or more days past due on dues. Projects that need critical repairs, certain pending litigation, hotel-style operation, or more than 35% commercial space can be ineligible. Requirements vary by lender and project.
What is a Nevada resale package and when do I get it?
It is a set of documents the association must provide within 10 calendar days of a written request, under NRS 116.4109. It includes the CC&Rs, bylaws, rules, current operating budget, and a financial statement with a reserve summary. The package stays effective for 90 days. Ask for it as soon as you are serious about a unit.
How do HOA dues affect how much I can borrow?
Lenders count HOA dues as part of your monthly housing expense when they calculate debt-to-income. In my example, $300 a month in dues adds 3.75 points to your ratio on $8,000 of gross monthly income and lowers the loan amount you can qualify for.
Can I use a VA loan on a condo?
Often yes, but the project generally has to be approved by VA. According to VA's lender pamphlet, projects already approved by HUD generally do not need a separate VA review. Ask your lender to check the project's status early, because rules change.
Mike Prenesti, NMLS #1033445. C2 Financial Corporation, NMLS #135622. Equal Housing Opportunity. Licensed in Nevada. This article is for educational purposes only and is not a commitment to lend or financial advice. Program availability, rates, and requirements vary by lender and borrower. Not all borrowers will qualify. Program guidelines vary by investor and are subject to change.
Have questions about your situation?
Let's talk it through. No pressure, no obligation.
Book a Free ConsultationRelated Posts
How Long It Really Takes to Close a Mortgage, Week by Week
From signed contract to keys, here is what happens each week, what slows each step down, and what you can do to keep your closing on schedule.
Renting vs. Buying in Las Vegas Right Now: What Each One Really Costs
At today's median price, owning costs more per month than renting a similar home. Here is the full math, what each path builds, and how long you need to stay.
Mortgage Broker vs. Bank: What Actually Wins You the Better Loan
A bank can only sell you what's on its own shelf. A broker shops your file across dozens of lenders to find the one that actually says yes, and says yes on better terms. Here's what that difference is worth.