Mike Prenesti, The Mortgage Jedi
16 years helping Las Vegas homebuyers find the right loan. NMLS #1033445.
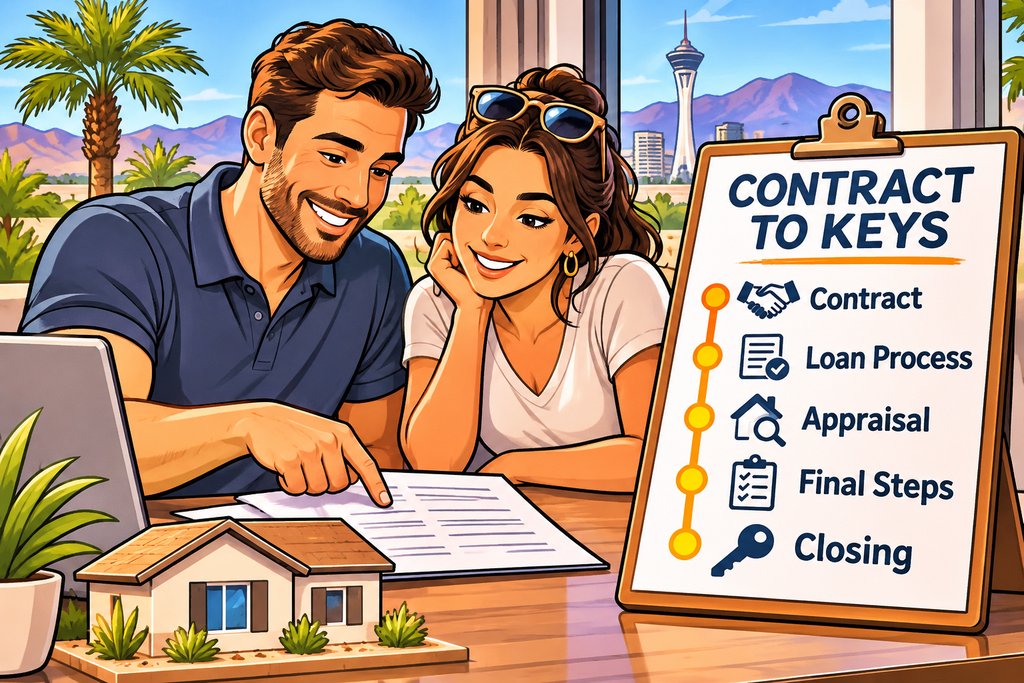
A typical purchase in Las Vegas closes in about 25 to 35 days from a signed contract. Some close faster, and some take longer.
For a national benchmark, ICE Mortgage Technology reported that the average purchase loan closed in 36.8 days in March 2026, the fastest it has recorded since it started tracking in 2019. That number starts the clock at the loan application, not the signed contract, so the two figures are not a direct match.
Here is how those weeks usually break down. Treat the timing as approximate, because every file is different.
Week 1: Contract, Escrow, and Rate Lock
Once the seller accepts your offer, you are under contract. Escrow opens at a title or escrow company, your earnest money goes in, and your inspection period starts running.
On the loan side, your lender receives the contract and gets your file moving. A Loan Estimate is due within three business days of a formal application, according to the Consumer Financial Protection Bureau.
This is also when most buyers lock their rate. ICE found that the typical purchase loan took 11 days from application to rate lock, then another 26 days from lock to closing. My post on rate locks explains how to match your lock period to your timeline.
The lender orders the appraisal in these first few days. Start gathering homeowners insurance quotes now, because the lender needs proof of coverage before closing.
Week 2: Appraisal and Processing
The appraiser visits the home and compares it to recent sales nearby. The report usually comes back within one to two weeks, depending on how busy appraisers are. My post on the appraisal process covers what happens if the value comes in low.
At the same time, a processor collects your documents. Expect requests for pay stubs, bank statements, and tax returns or other income documents, depending on your loan. The title company is also working in the background, searching the property's ownership history for liens or other problems.
Weeks 2 to 3: Underwriting
The underwriter reviews the whole file at once: your income, your assets, your credit, the appraisal, and the title report. This is the decision point for your loan.
Most files do not come back as a clean yes. The usual result is an approval with conditions, which is a list of items the lender still needs. That is normal and does not mean something is wrong.
Weeks 3 to 4: Conditions
Conditions might include a letter explaining a deposit, an updated bank statement, a verification of employment, or proof of a gift. Each one you answer quickly keeps the file moving, and each one that sits for days adds days to your closing.
If family is helping with your down payment, tell your lender before the money moves. The paperwork is simple when it is ready from the start and slow when it is not.
Week 4: Clear to Close and the Three-Day Window
Clear to close means underwriting has approved your loan and every condition is met. The lender prepares the final documents, including your Closing Disclosure.
The CFPB says your lender must make sure you receive the Closing Disclosure at least three business days before closing. Sundays and federal holidays do not count. A significant change after you receive it, such as a different loan product, can restart that wait.
Use those three days to compare the Closing Disclosure to your original Loan Estimate and ask about anything that moved. My post on closing costs shows where the numbers come from. This is also when you do your final walkthrough and confirm how you will send your cash to close.
If you wire funds, confirm the instructions by calling a phone number you already know is real. Wire fraud targets buyers at exactly this stage.
Closing Day: Signing, Funding, and Recording
You sign your documents at the title or escrow office, or with a mobile notary if you set that up. Bring a valid photo ID.
After you sign, the lender funds the loan, and the deed records with the county. You get the keys when that is done. It can happen the same day you sign or the next business day, depending on when the lender funds and how the title company works.
What Slows a Closing Down
A few things cause most of the delays.
- A late appraisal, or a value that comes in below the price.
- Open conditions that sit while a document gets tracked down.
- New debt, a new credit card, or a large unexplained deposit. Underwriters re-check your file close to closing.
- Complicated income, such as self-employment, which takes more documentation.
- Title issues, like a lien or an ownership question that has to be cleared.
- Homeowners insurance that is not bound in time.
- A rate lock that expires before closing.
Government loans can also take longer. In ICE data reported by CNBC, conventional purchases averaged 42 days in June 2025, with FHA and VA loans running longer.
How to Keep Yours on Track
Start with a full pre-approval before you shop. My post on pre-approval letters explains why an underwritten letter is faster than a quick estimate.
Order homeowners insurance as soon as you are under contract. Answer every document request the same day, even if the answer is only that you are working on it. Keep your finances steady until you have the keys, which means no new credit, no job change, and no large deposits without paperwork.
No timeline is guaranteed, and some delays are outside your control. But the buyers who close on time are usually the ones who stayed ahead of the paperwork. If this is your first purchase, my first-time buyer guide covers the full process in order.
If you want a realistic timeline for your own purchase, I am happy to walk through it with you. See if we're a fit or book a call directly.
Frequently Asked Questions
How long does it take to close on a house in Las Vegas?
In my files, a clean purchase usually closes in 25 to 35 days from the signed contract. Nationally, ICE Mortgage Technology reported that the average purchase loan took 36.8 days from application to closing in March 2026. FHA and VA loans, new construction, and files with open questions can take longer.
What is the three-day Closing Disclosure rule?
Your lender must make sure you receive the Closing Disclosure at least three business days before you close. Sundays and federal holidays do not count. A significant change, such as a different loan product, can restart the wait.
What does clear to close mean?
It means underwriting has approved your loan and every condition has been met. The lender then prepares the final documents and the Closing Disclosure. It is the green light, but the three-day wait and the signing still come after it.
What can delay a mortgage closing?
Common causes are a late or low appraisal, open underwriting conditions, slow responses to document requests, title issues, homeowners insurance that is not in place, and new debt or large unexplained deposits. Most of these are avoidable if you respond quickly and keep your finances steady.
Can I speed up my closing?
Often, yes. Get a full pre-approval before you shop, order your homeowners insurance early, answer every request the same day, and avoid new credit or large deposits. Some things, such as appraisal scheduling and title work, are outside your control.
When do I get the keys?
Usually after you sign, the lender funds the loan, and the deed records with the county. That can happen the same day you sign or the next business day, depending on the lender's funding schedule and the title company. Your agent and escrow officer will confirm the timing.
Mike Prenesti, NMLS #1033445. C2 Financial Corporation, NMLS #135622. Equal Housing Opportunity. Licensed in Nevada. This article is for educational purposes only and is not a commitment to lend or financial advice. Program availability, rates, and requirements vary by lender and borrower. Not all borrowers will qualify. Program guidelines vary by investor and are subject to change.
Have questions about your situation?
Let's talk it through. No pressure, no obligation.
Book a Free ConsultationRelated Posts
Renting vs. Buying in Las Vegas Right Now: What Each One Really Costs
At today's median price, owning costs more per month than renting a similar home. Here is the full math, what each path builds, and how long you need to stay.
Mortgage Broker vs. Bank: What Actually Wins You the Better Loan
A bank can only sell you what's on its own shelf. A broker shops your file across dozens of lenders to find the one that actually says yes, and says yes on better terms. Here's what that difference is worth.
Nevada Property Taxes: What New Homeowners Actually Pay (And the Filing Mistake That Costs Thousands)
Nevada has some of the lowest property tax rates in the country, but one unfiled form can bump your annual increase cap from 3% to 8%. Here is how the bill works, what it adds to your payment, and what to file after you close.